- Financing Options for ADUs in California: Loans, HELOCs, and More
- Understanding ADU Development Costs
- Home Equity Lines of Credit (HELOCs) for ADUs
- Cash-Out Refinancing as a Funding Option
- Government Programs and Incentives
- Personal Savings and Investment Options
- Making the Best Financial Decision for Your ADU
Financing Options for ADUs in California: Loans, HELOCs, and More
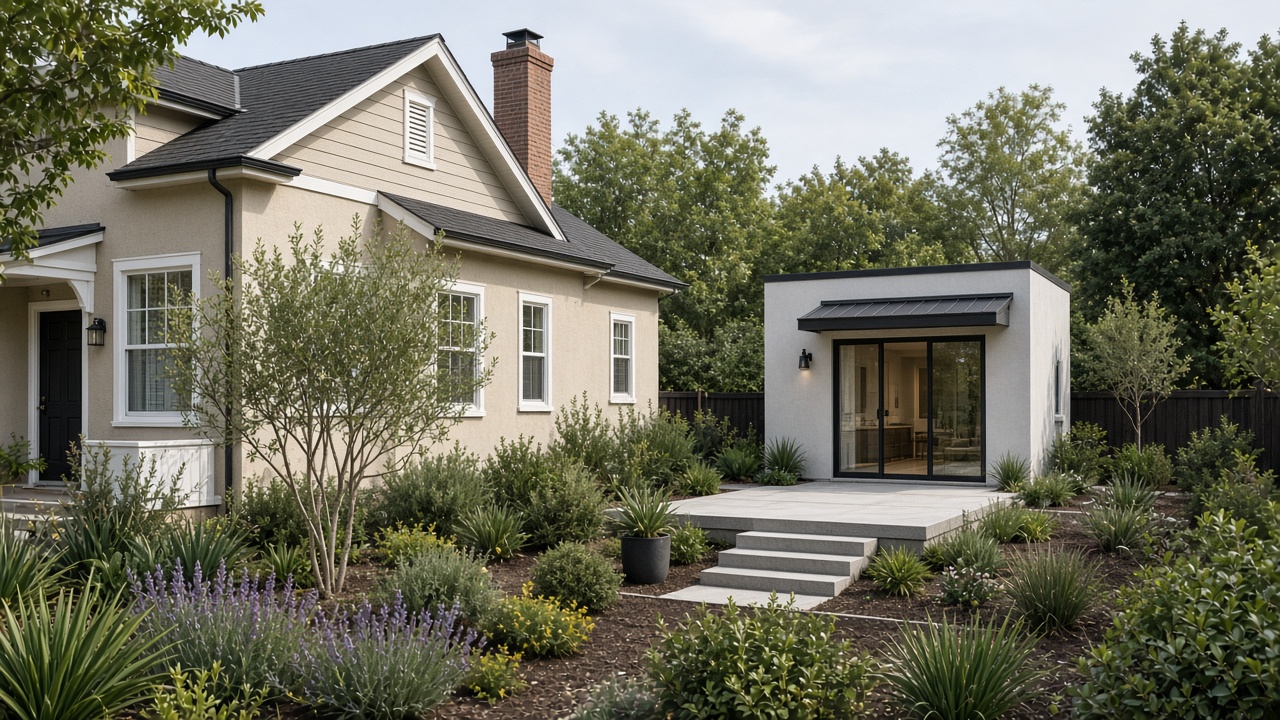
For Tim and Lisa, a couple living in sunny California, the idea of transforming their garage into an Accessory Dwelling Unit (ADU) was, well, more than just a renovation project. It was a chance to bring in extra income and maybe even create a cozy nest for the in-laws. Yet, the question hung in the air: How on earth would they pay for it?
ADUs, or Accessory Dwelling Units, are small residences that share the same lot as a primary home. They’re the darling of urban planners and a clever solution to housing shortages. But for most homeowners, ADU construction hinges on one all-important factor: financing. In California, a state renowned for its innovation and, let’s admit, its high property prices, understanding the available financing options can be your ticket to constructing that dream space.
Understanding ADU Development Costs
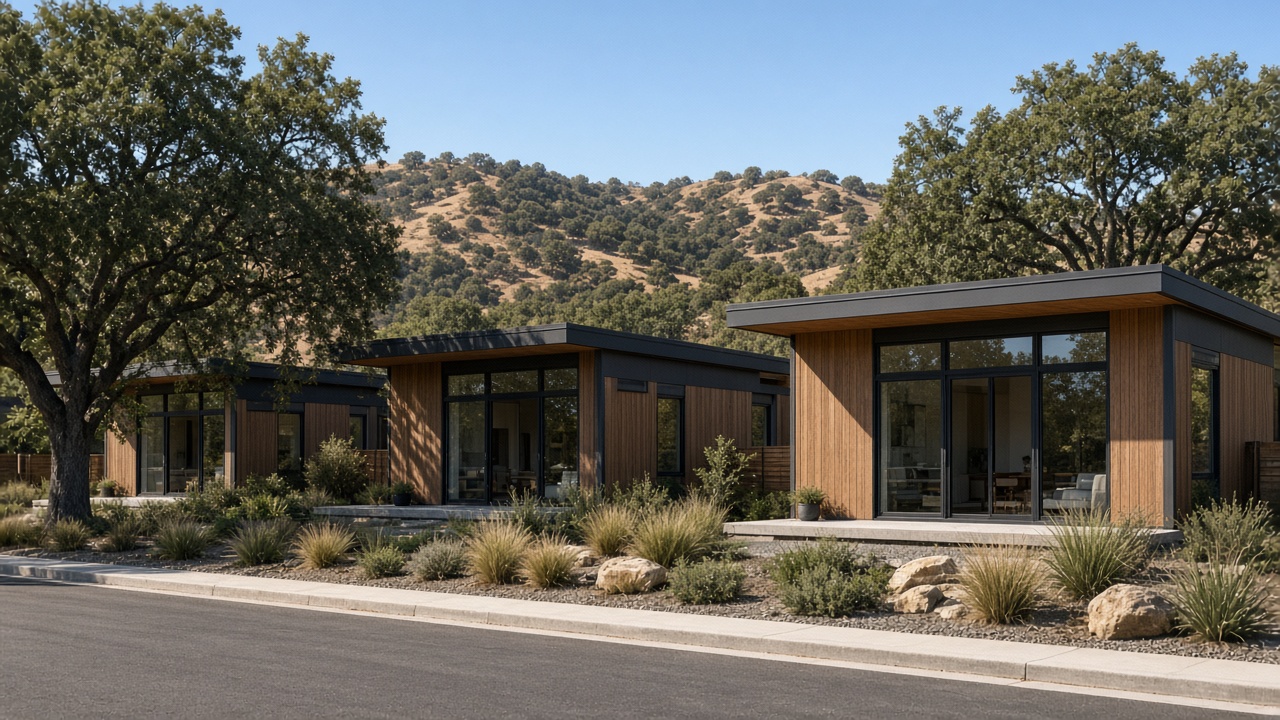
Building an ADU isn’t just about adding square footage; it’s a full-fledged construction project, complete with its own set of costs and surprises. Typical costs can range widely, influenced by factors like location, design complexity, and materials. Before you start dreaming of bamboo floors and rooftop gardens, financial planning becomes your strongest tool.
To get a grip on your budget, consider everything from permits to utility connections. The goal? Avoiding those pesky surprise expenses that can stretch your financial limits. Because in the world of ADU construction, preparation is practically your best friend.
Home Equity Lines of Credit (HELOCs) for ADUs
Imagine your home’s value is like a treasure chest. A Home Equity Line of Credit (HELOC) is one way to access that treasure. Functioning much like a credit card, a HELOC lets you borrow against the equity of your home, giving you a flexible funding source for your ADU construction.
Why choose a HELOC? For many, it’s the flexibility draw funds as needed while only paying interest on the drawn amount. Yet, as with any loan against your home, there are risks. Should property values fall, you could end up owing more than your home is worth. HELOCs often suit scenarios where the construction budget is uncertain and needs some fluidity.
Cash-Out Refinancing as a Funding Option
Enter cash-out refinancing, where you replace your existing mortgage with a new one, pocketing the extra funds. It’s a bit like cashing in your chips for a bigger stack, using the difference to fund your new ADU.
While this option can offer lower interest rates and a larger lump sum than other options, it does come with the downside of potentially extending your mortgage term or increasing your monthly payments. For homeowners with substantial equity, it can be a powerful tool, but it requires careful weighing of long-term impact on finances.
Government Programs and Incentives
Don’t overlook the support from Uncle Sam. In California, a range of government programs, both federal and state, provide incentives for ADU development. These can include tax credits, deductions, or even grants designed to ease the financial burden.
Eligibility can vary, often depending on location and income. The application process might seem daunting at first, but the financial relief it offers can be substantial. Tapping into these resources can make your ADU project not just a dream, but an affordable reality.
Personal Savings and Investment Options
Personal savings play a critical role in ADU financing, especially for those who prefer not to take on additional debt. Utilizing savings can minimize interest payments and keep your financial health in check. But dipping into your savings requires balance is the immediate expenditure worth the long-term return?
Alternative investments, such as using a portion of your retirement fund or exploring joint ventures with other investors, can also furnish the necessary funds. Strategic long-term planning ensures that even as you build your ADU, you’re not sacrificing future financial stability.
Making the Best Financial Decision for Your ADU
So, how do Tim and Lisa, and you, make the best financial decision for an ADU? It starts with evaluating the various financing options through a personal lens. Your circumstances, from equity to income to risk tolerance, will shape the path you take. Engaging with a financial advisor can add a layer of expertise, ensuring you manage financial risk while promoting sustainable growth.
Key Points:
- Evaluate your specific financial situation and project needs.
- Consider consulting financial professionals for tailored advice.
- Stay informed about local incentives that could ease the financial burden.
Remember, building an ADU is not just a construction project, but a financial journey that, with the right approach, can enhance both your property and your peace of mind.